

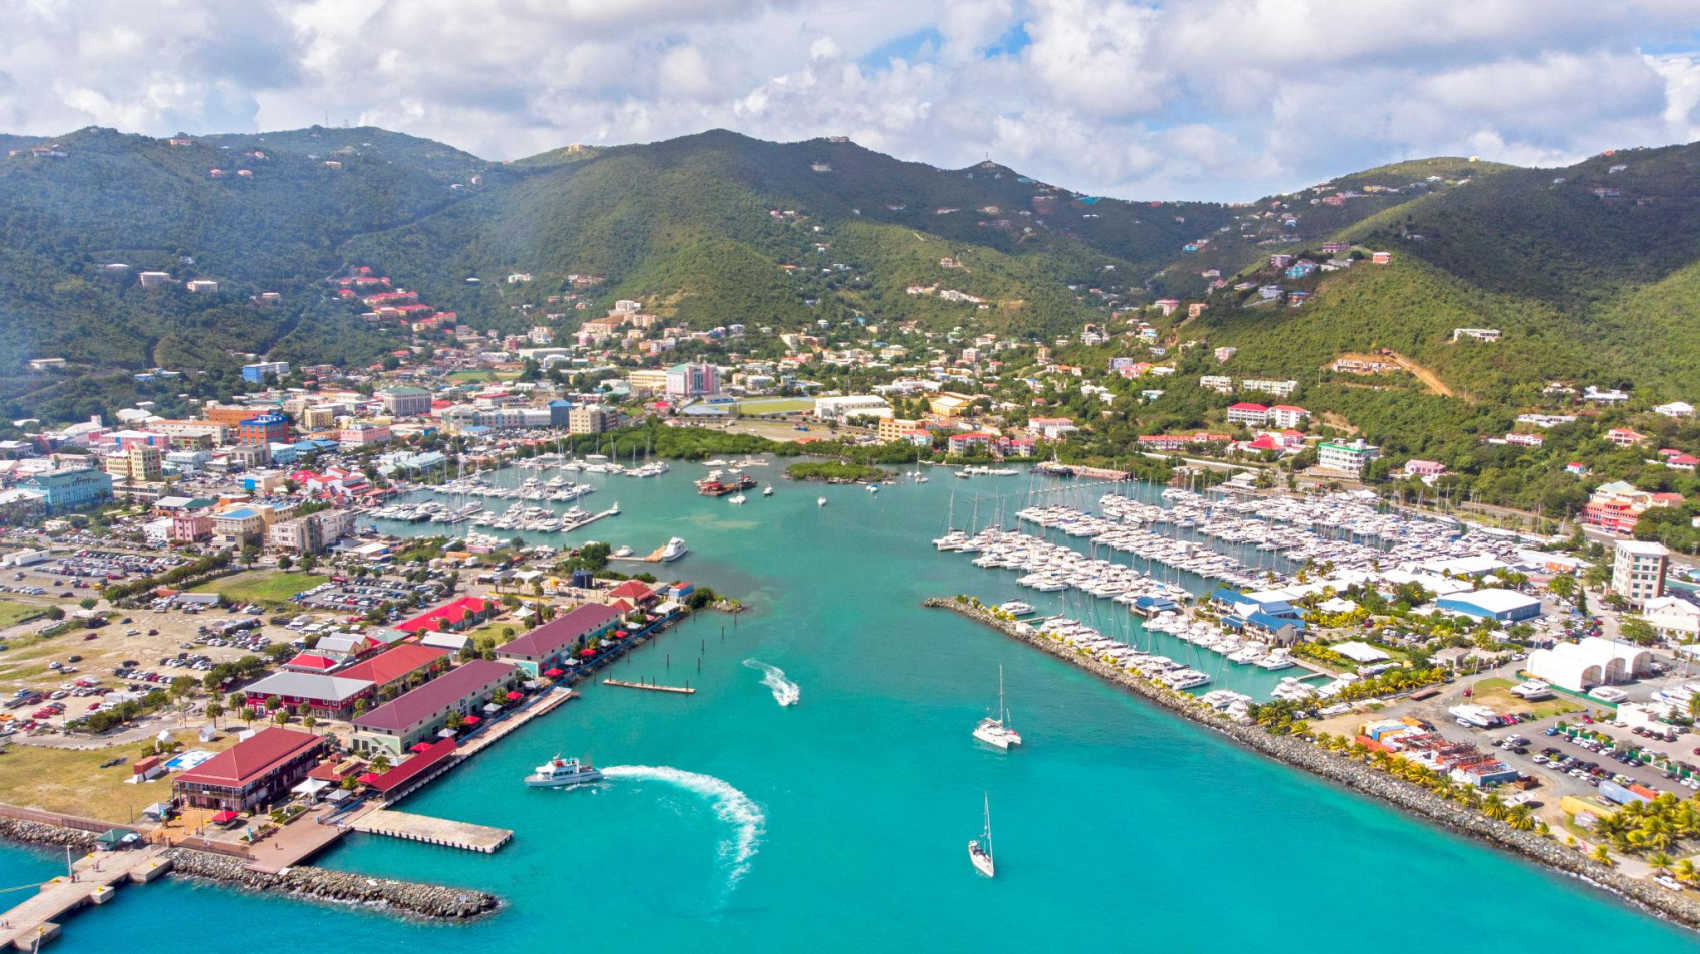
The British Virgin Islands remains under increased international monitoring for money laundering and other financial crime risks, despite making progress in corporate ownership transparency, suspicious transaction reporting and law-enforcement capacity, according to a new assessment by the Financial Action Task Force.
In its October 30 assessment, issued following a plenary meeting in Paris, the international financial watchdog retained the BVI on its so-called grey list, identifying outstanding weaknesses in oversight of financial businesses, money-laundering investigations, criminal prosecutions and the seizure of illicit proceeds.
The decision comes more than 16 months after the British overseas territory was placed under increased monitoring in June 2025. While the FATF removed Bulgaria, Côte d'Ivoire, the Democratic Republic of the Congo and Monaco from the grey list following its October meeting, the BVI was among the jurisdictions required to continue implementing corrective measures.
The designation applies to the British Virgin Islands, not the U.S. Virgin Islands.
The FATF acknowledged several improvements achieved by BVI authorities since the territory committed to strengthening its financial crime prevention framework. These included making accurate and current information about the individuals who ultimately own companies available to competent authorities, improving the quality of suspicious activity reports submitted by financial institutions and increasing staffing within law-enforcement agencies.
However, the organization identified five areas where additional action remains necessary before the territory can satisfy its corrective action plan.
Financial oversight, prosecutions and asset seizures remain concerns
Among the outstanding requirements is stronger risk-based supervision of trust and company service providers, investment businesses and virtual asset service providers, which include certain companies handling cryptocurrency and other digital assets.
The FATF also wants BVI authorities to demonstrate that companies and other regulated entities face appropriate sanctions when they violate beneficial ownership reporting obligations.
Beneficial ownership requirements are intended to establish who ultimately owns or controls a company, reducing opportunities for individuals to conceal assets or conduct illicit transactions through complex corporate structures.
Although the FATF acknowledged improvements in the availability of such information, it determined that the territory must do more to enforce compliance when those obligations are breached.
The watchdog separately called for improvements in the sharing of financial intelligence in international cases, more systematic pursuit of money-laundering investigations and prosecutions consistent with the territory's financial crime risks, and increased seizure and confiscation of criminal proceeds.
These requirements focus not only on whether the BVI has adopted adequate financial crime laws and regulations, but also on whether authorities are effectively using those powers to investigate wrongdoing, prosecute offenders and recover illicit assets.
That distinction is particularly important because an earlier Caribbean Financial Action Task Force follow-up assessment found that the territory had achieved compliant or largely compliant ratings across all 40 FATF technical recommendations.
Despite those ratings, the BVI remained subject to additional monitoring because of concerns about how effectively its financial crime controls operate in practice.
BVI government says reforms remain on schedule for 2027
The BVI government welcomed the recognition of progress, saying it remains committed to completing outstanding reforms under its national anti-money-laundering action plan.
In an October 30 statement, the government said its delegation to the Paris meetings was led by Lorna Smith, Junior Minister for Financial Services and Economic Development, and Attorney General Dawn J. Smith.
The delegation also included Glenford Malone, deputy managing director for regulation at the Financial Services Commission, and Ayana Glasgow, director of financial services within the Ministry of Financial Services, Economic Development and Digital Transformation.
According to the government, the latest meeting represented the territory's third formal report to the FATF since entering the increased monitoring process.
Officials said the territory has improved its understanding of financial crime threats, strengthened regulatory oversight and expanded law-enforcement and prosecution capacity.
Attorney General Smith said the government would continue its efforts to "complete the outstanding actions within the agreed timeframe."
Lorna Smith similarly maintained that the territory was "well on track to meet our commitments in 2027."
The government's stated objective is to complete its corrective measures in 2027. However, the FATF has not announced a specific date for removing the BVI from the grey list, and completion of the government's planned reforms would still require international assessment.
Financial services remain central to BVI government revenue
The outcome carries considerable importance for the British Virgin Islands, where financial services represent a major source of government revenue and support economic activity beyond the tourism sector.
In his October 27 budget address for 2027, Premier Natalio Wheatley projected that financial services would generate approximately $226.1 million in government revenue for 2026, against total projected government revenue of $454.4 million.
The government has made protecting the sector's international reputation and regulatory credibility a priority as it pursues additional overseas business and financial services development.
Wheatley also outlined plans to expand specialist capacity within the Office of the Director of Public Prosecutions, the Royal Virgin Islands Police Force and His Majesty's Customs, including expertise in financial crime investigations, asset recovery and terrorist financing.
The continued grey-list designation carries international compliance implications, although it does not amount to a ban on doing business with the territory.
The FATF explicitly states that its increased monitoring process does not itself require financial institutions to apply blanket enhanced due diligence to every transaction involving a listed jurisdiction. Instead, it urges regulators and financial institutions to use a risk-based approach rather than indiscriminately terminating customer relationships.
Separate jurisdictions may nevertheless impose additional obligations under their own laws.
The European Commission, for example, also lists the British Virgin Islands among its high-risk third countries for anti-money-laundering purposes, a designation that took effect January 29, 2026. European Union requirements call for additional checks and controls involving business relationships and transactions linked to listed jurisdictions.
The continued FATF monitoring therefore comes as the BVI works to demonstrate not simply that its regulations meet international standards, but that its enforcement agencies can produce measurable results.
The October assessment did not establish how many additional prosecutions, confiscations or regulatory sanctions would be needed to satisfy the remaining requirements.
For now, the territory remains on the international watchlist, with its government targeting completion of outstanding reforms in 2027 and the FATF continuing to assess whether those measures have delivered the required improvements.